Margin Debt Is Flashing a Rare Stock Market Warning
Margin debt has surged to a record $1.5 trillion, creating a rare market warning seen only a few times since 1997. History shows why investors should pay attention.
Margin Debt Is Flashing a Rare Stock Market Warning
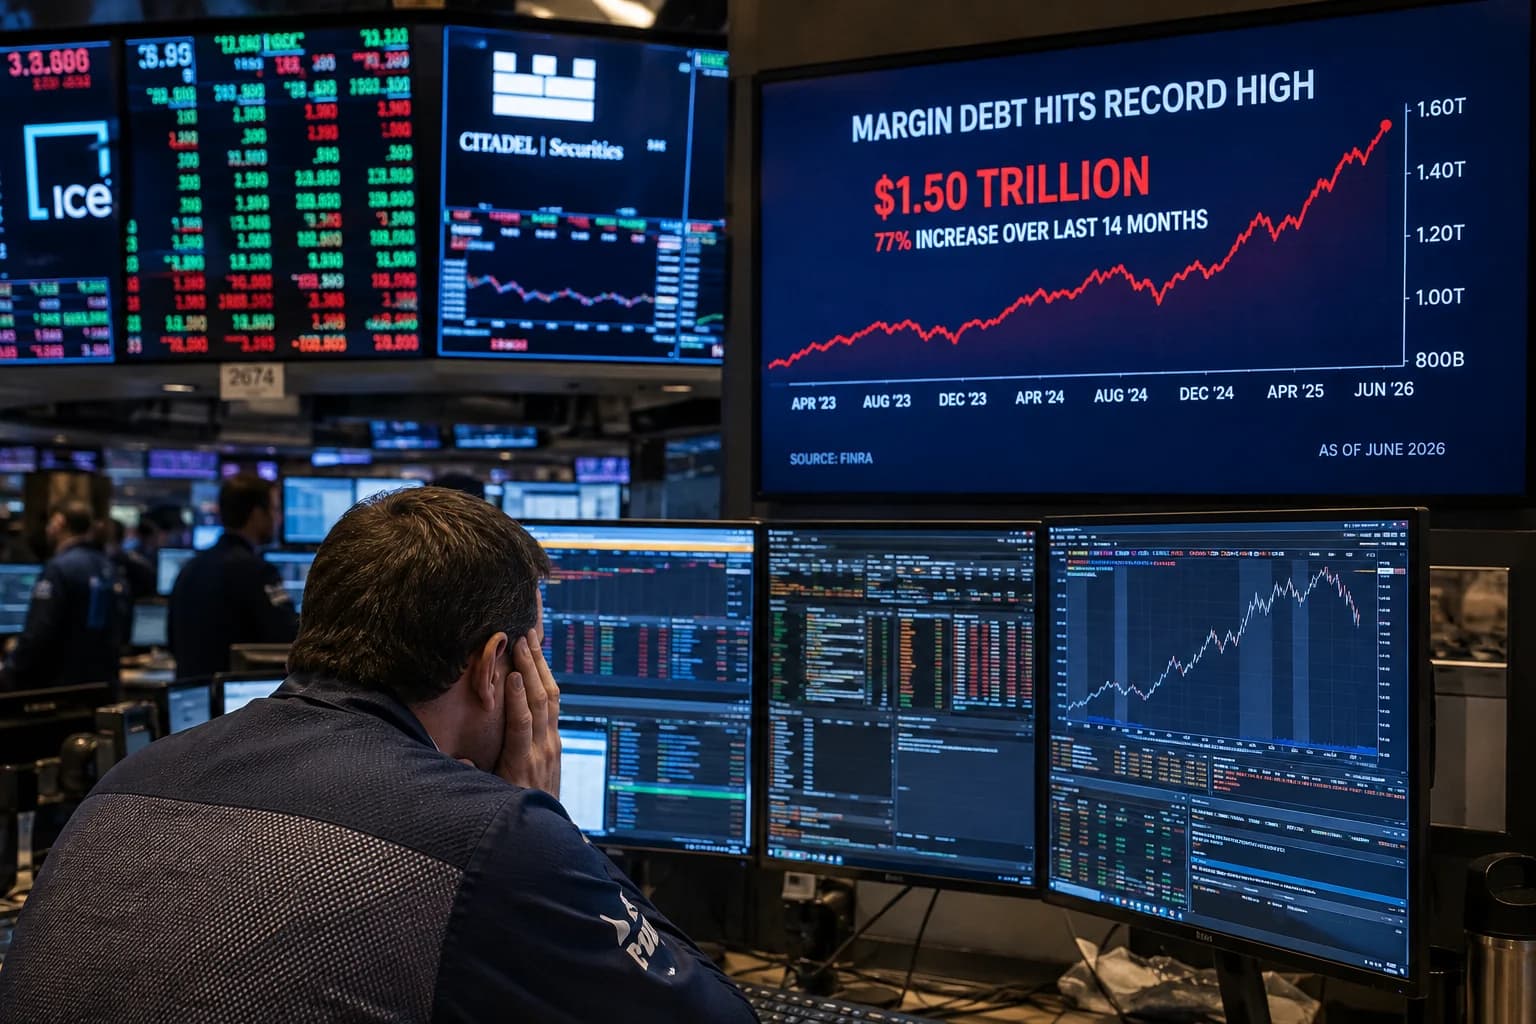
The U.S. stock market is showing a pattern that has appeared only four times since 1997: outstanding margin debt has surged at least 65% over a relatively short period. FINRA data show margin debt reached a record $1.502 trillion in June 2026, up 77% from $850.6 billion in April 2025. The previous three episodes occurred around the 2000 dot-com bubble, the 2007 financial crisis, and the 2021 market peak, each followed by a major equity downturn.
That history makes margin debt worth watching, but it does not mean a crash is automatically next. The SP 500 itself remains near record highs, having closed at another record on August 7, while corporate earnings have remained strong. The signal is better understood as a measure of how much borrowed money is supporting the market rather than as a precise countdown to a sell-off.
Why Rising Margin Debt Can Become a Market Problem
Margin debt is money investors borrow from their brokers to buy securities. Borrowing can magnify gains when stocks rise, but it also increases the damage when prices fall. A leveraged investor can face a margin call if the value of the securities supporting the loan drops far enough, forcing the investor to add cash or sell holdings.
That creates a potential feedback loop. Falling prices reduce collateral values, which can force leveraged investors to sell. Those sales can push prices lower, putting additional leveraged portfolios under pressure. Margin debt therefore becomes most concerning when it rises rapidly at the same time that investors are paying elevated prices for stocks.
The Four Margin Debt Episodes Since 1997
The historical pattern is unusually concentrated. From March 1999 to March 2000, margin debt jumped about 80% in 12 months as the dot-com bubble approached its peak. The Nasdaq subsequently fell about 78% from its March 2000 high to its 2002 low.
The second major episode ran from June 2006 to July 2007, when margin debt increased about 66% in 13 months. The SP 500 reached its pre-financial-crisis peak later in 2007 before the global financial crisis produced a much deeper decline. The third episode occurred around 2021, when margin borrowing expanded rapidly before the 2022 bear market, during which the SP 500 fell about 25% from its high to its low.
The fourth episode is the one unfolding now. Margin debt increased from $850.6 billion in April 2025 to $1.502 trillion in June 2026, an increase of roughly 77%. FINRA's own statistics show the underlying debit-balance series and confirm that these figures are collected monthly from member firms.
Margin Debt Is Not the Same as a Guaranteed Crash Signal
The historical record is striking, but it is also easy to overstate. The three earlier episodes did not cause market declines simply because investors borrowed money. Margin debt usually rises during powerful bull markets because investors have more collateral and greater confidence. The important feature is the speed and scale of the increase, not merely the fact that debt is at a record.
There is another limitation: FINRA's margin statistics are reported with a delay and measure aggregate customer debit balances rather than every form of financial leverage in the market. FINRA also notes that changes in reporting practices can affect historical comparisons. That makes margin debt useful as a risk indicator, but not a standalone market-timing tool.
Why Today's Market Could Still Defy the Historical Pattern
The current market has characteristics that were less prominent in some previous episodes. Corporate earnings are supporting much of the rally, particularly through enormous investment in artificial intelligence infrastructure. Reuters reported that second-quarter 2026 earnings growth was running at 31.1% year over year among the SP 500 companies reporting, with technology-sector earnings up 72%. That gives today's market a stronger fundamental foundation than a simple comparison with the dot-com era would suggest.
Valuations also look different depending on the measure used. The Shiller CAPE ratio has moved above 42, a historically elevated level, while forward valuation measures have fallen as earnings have caught up with prices. Recent market coverage has highlighted that tension: some valuation measures remain expensive, while others suggest the market has become less stretched as profits rise.
What Investors Should Watch Next
The most useful question is not whether margin debt predicts a crash on a particular date. It is whether the leverage buildup is followed by deterioration in the conditions that allowed investors to carry that leverage. Falling earnings expectations, tighter financial conditions, weakening market breadth or a sharp decline in risk appetite would make the margin-debt signal more significant.
Investors should also watch whether margin borrowing continues climbing faster than the underlying market and economy. June's $1.502 trillion balance was already an all-time high, and the increase from April 2025 was much faster than the long-term upward trend that naturally occurs as the U.S. financial market grows.
The Real Lesson From the Four Episodes
The historical lesson is less dramatic than "a crash is coming." It is that rapidly expanding leverage can leave the market more vulnerable when sentiment changes. The previous three episodes eventually coincided with severe losses, but the margin-debt surge itself did not identify the exact day, month or trigger of those downturns.
For investors, that distinction matters. A record margin balance is a reason to reassess portfolio risk, position sizing and dependence on continued market gains. It is not, by itself, a reason to assume that stocks must immediately collapse. The SP 500's ability to keep reaching records while leverage rises shows why this signal deserves attention without turning it into a prediction it cannot reliably make.